Unreleased Mortgages and Missing Heirs: Why Your 18th-Century Easton Home Needs a 100-Year Title Review
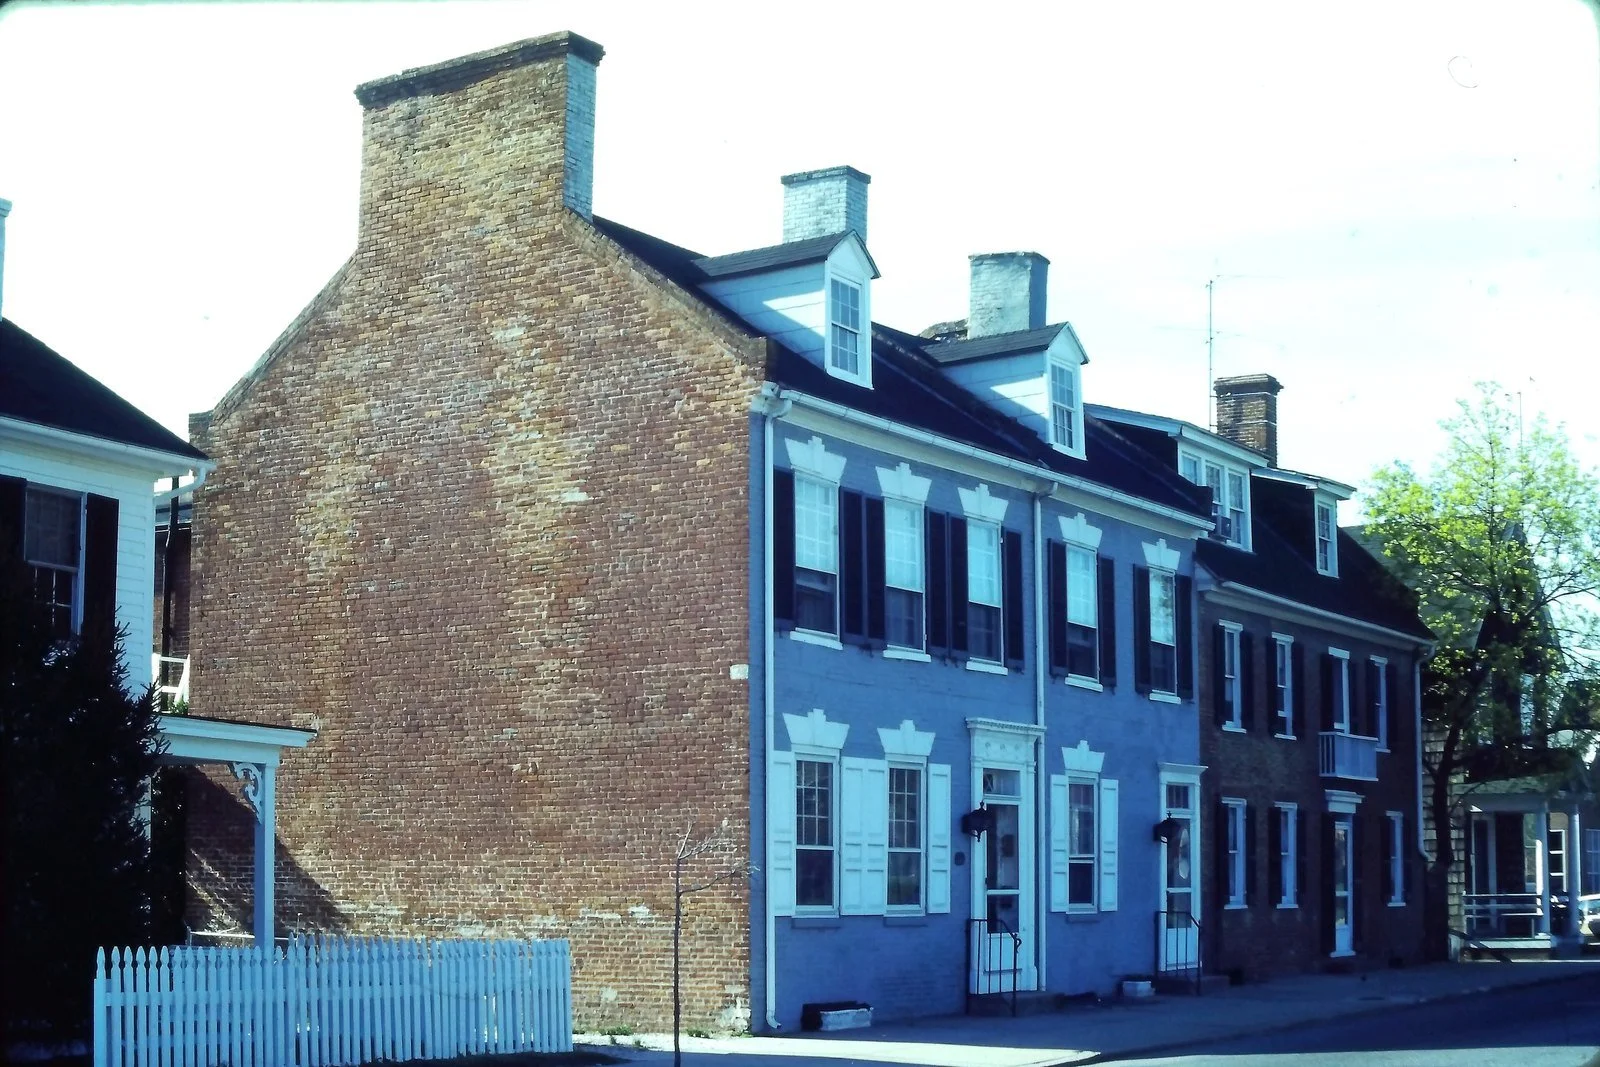
Photo: Federal-era houses on South Washington Street in Easton. Credit Bmzuckerman, CC BY 4.0, via Wikimedia Commons.
The historic elegance of downtown Easton, and the charm of properties in towns like Trappe, is part of what makes Talbot County what it is. That age also creates real work for a title examiner.
When a property's history reaches back to the 1700s, the chain of ownership is long, the handwriting is hard, and the record is not always complete. Two problems come up again and again.
Unreleased mortgages
A mortgage gets paid off, the note is marked paid, and everyone moves on. What sometimes never happens is the recording of a release in the land records. Decades later, the original lender may be gone, the loan file destroyed, and the county record still shows an open mortgage against the property.
That is a cloud on the title. It has to be cleared before a buyer's lender will close, and clearing it means proving the debt was satisfied, or obtaining a release from whoever holds the rights to it now. Sometimes a title insurance underwriter resolves the matter instead, with the record documented.
Missing heirs and estate gaps
When a property passes through an estate, every heir with an interest needs to be accounted for. In old family transfers, that did not always happen. A deed might name three of four children. A surviving spouse may have remarried and conveyed property that was not solely theirs to convey. A will may exist but never have been probated.
None of this matters for eighty years. Then a sale comes along and one signature on a 1948 deed becomes the difference between a clean closing and a delayed one.
How long we look, and why
Maryland has a marketable record title statute that limits how far back a search generally has to reach, but the statute is not a magic eraser. Exceptions exist, and recorded instruments outside the period can still matter if they are properly indexed and referenced.
For properties with significant age, we look back further than the minimum. On a house that has been in one family for generations, we also look sideways: the probate file, the tax records, the old plats. The point is not to generate paperwork. The point is to find the problem while there is still time to solve it.
What this means if you are buying or selling
Start earlier than you think you need to. A historic property can take several weeks to clear. A contract written with a two-week closing date on an 1800s house is a contract built to be extended.
Expect an affidavit or two. When a record is genuinely missing, a seller's affidavit, an heir search, or a quiet title action may be the answer. All of them are routine when they are identified early and painful when they are identified late.
Tell your agent what you know. Whether the property has been in the family, whether an old mortgage was paid off, whether the estate was handled: all of it helps.
Ask before you list. A seller who knows about a title issue in advance can clear it, price around it, or disclose it. A seller who finds out at settlement day inherits the buyer's problem and the buyer's timeline.
Call us at 410.820.4426 before you list or before your contract's title contingency runs. On a house this old, a little patience at the front end saves a great deal of trouble at the back.